Do I need a financial adviser?
We look at your pensions, savings and cover with you and say where advice would change the outcome in pounds.
We look at your pensions, savings and cover with you and say where advice would change the outcome in pounds.
The law requires regulated advice before you transfer safeguarded pension benefits worth more than £30,000, such as a final salary pension. For a pension with no guarantees, an ISA or an investment, taking advice is your choice.
Advice changes the most in pounds on decisions that are hard to reverse: giving up a guaranteed pension, buying an annuity, or taking a large sum out of a pension in a single tax year.
A complimentary health check is how to find out whether your own position needs advice. An adviser looks at your pensions, savings, investments, mortgage and cover with you, by phone or video.
The advisers for this subject: Sunny Bharj and Tony Springer
Safeguarded benefits are guarantees a pension scheme has promised you, most often an income for life from a final salary or career average scheme. Transfers of safeguarded benefits worth more than £30,000 require regulated advice by law, and a scheme will not process one without it.
Defined benefit transfer advice sits behind its own FCA permission, separate from ordinary pension advice, and the regulator requires the adviser to start from the assumption that a transfer is unsuitable.
A pension with no safeguarded benefits can be moved without advice. Older plans can still carry a guaranteed annuity rate or protected tax-free cash that a transfer gives up.
A deferred pension keeps its guarantees after you leave. Advice is compulsory before a transfer worth more than £30,000.
Normally 25% comes out free of tax and the rest is taxed as income. The minimum age rises to 57 on 6 April 2028.
No employer pays in, so every contribution comes from you, with tax relief at your marginal rate.
An ISA takes £20,000 a year and a pension up to £60,000, or your earnings if lower. Gifts to your family have their own rules.
A fee, commission or a percentage of the money. Ask for the charge in pounds before you proceed.
Pension Wise, the government's guidance service from MoneyHelper, offers free appointments to people aged 50 and over with a defined contribution pension. It sets out the options open to you without recommending one.
Regulated advice ends in a personal recommendation for your circumstances. Before you agree to anything you have the recommendation and the price in pounds, and you are free to say no.
For one kind of pension transfer. Transfers of safeguarded benefits worth more than £30,000, such as a final salary pension, require regulated advice by law, and the scheme will not process the transfer without it.
Yes, where the pension holds no safeguarded benefits. Check the old plan for a guaranteed annuity rate, protected tax-free cash or an exit charge before it moves.
It is at no cost to you, and so is the health check. Any charge for later work is set out in pounds before it starts.
Yes. We advise people across the UK by phone and video, from one office in London.
Pension benefits and their tax treatment depend on your circumstances and on current rules, which can change. Transferring out of a defined benefit scheme means giving up guaranteed benefits, and is appropriate only in some circumstances. Any recommendation depends on a full assessment of your circumstances.
By law only for safeguarded benefits worth more than £30,000, such as a final salary pension. Other pensions can be moved without it.
Read the answer →A deferred pension keeps its guarantees after you leave the job. Ask the scheme what it will pay you before you look at the transfer value.
Read the answer →A fee or a percentage of the amount invested or transferred. Ask for the charge in pounds before you proceed.
Read the answer →You can, and 25% normally comes out free of tax. Taking taxable income cuts what you can pay back in to £10,000 a year.
Read the answer →Open a personal pension or join Nest. Contributions get tax relief at your marginal rate, up to £60,000 or your earnings if lower.
Read the answer →Hold it in cash while you decide. The estate settles the inheritance tax, and an ISA, a pension and gifts each have their own limits.
Read the answer →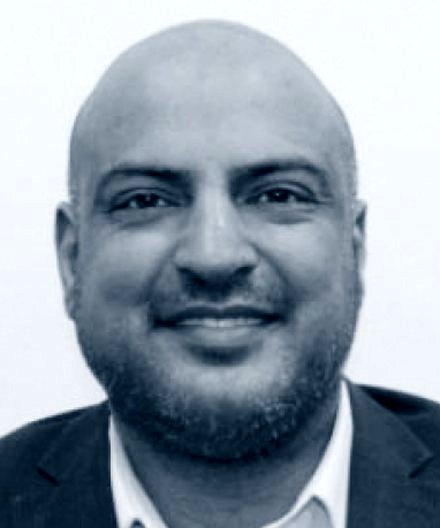
Independent Financial Adviser
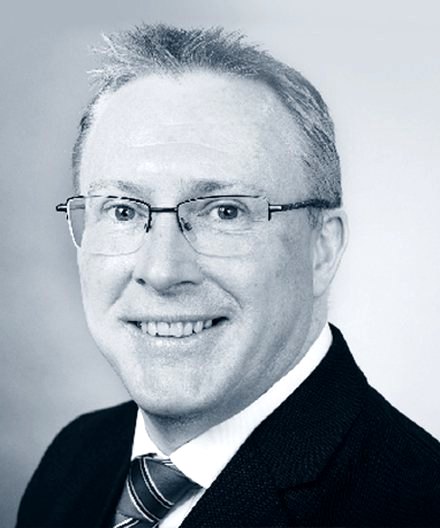
Independent Financial Adviser
Twenty statements about money that sort into four patterns, with a written report on the pattern your answers fit.
Your first call is with an Account Manager and is at no cost to you. Tell us what is on your mind: a pension you have lost track of, a fixed rate ending, a will you keep meaning to write.