What is a SIPP pension?
A SIPP, or self-invested personal pension, is a personal pension in which you choose the specific investments.
A SIPP, or self-invested personal pension, is a personal pension in which you choose the specific investments.
It follows the same tax rules as any other personal pension: tax relief on what you pay in, the £60,000 annual allowance, and access from 55, rising to 57 on 6 April 2028.
The advisers for this subject: Sunny Bharj and Tony Springer
The provider claims basic rate relief of 20% from the government and adds it to your pot, so a payment of £80 becomes £100.
They claim it through Self Assessment: a further 20% on income you paid 40% tax on, and a further 25% on income you paid 45% tax on. Scotland's rates differ. Pension tax relief in Scotland
You get relief on personal contributions up to 100% of your earnings in the tax year. With no earnings, relief is given on contributions up to £2,880.
Contributions from an employer are not limited by your earnings. Both count toward the £60,000 annual allowance.
Each provider sets its own list of the investments it will accept.
A SIPP follows the same tax rules as every other personal pension. What differs is who chooses the investments.
It is a type of personal pension. The difference is the range of investments and your control over them. Tax relief, allowances and access ages are the same.
Yes. The annual allowance covers both, so contributions to each count toward the same £60,000 limit.
Yes. With no earnings, the provider adds 20% relief on contributions up to £2,880 in the tax year.
You do, or an investment manager or adviser you appoint. The provider runs the scheme and holds the assets.
From most schemes, yes, where the old scheme allows it and the SIPP provider accepts it. Some pensions carry guarantees that a transfer gives up. Can I transfer my pension into a SIPP?
Before you choose a SIPP, list the investments you intend to hold and ask each provider for its annual charges in pounds on that portfolio.
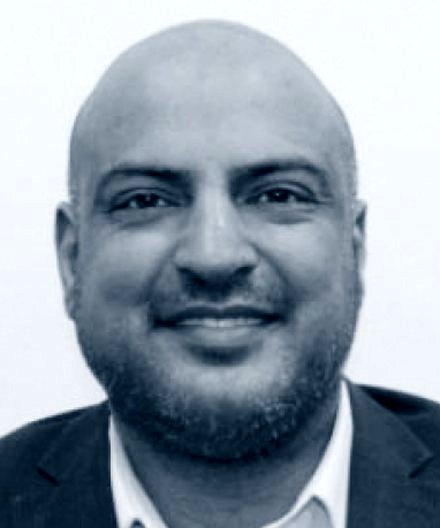
Independent Financial Adviser
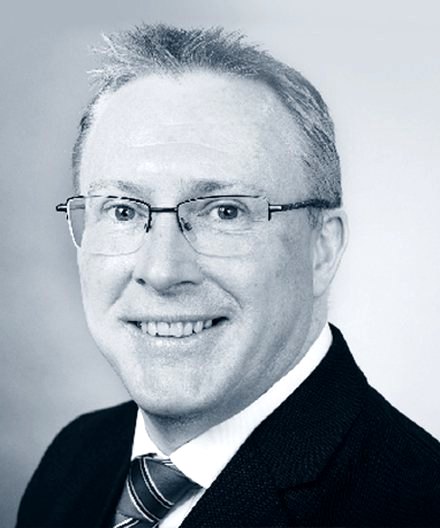
Independent Financial Adviser
Your first call is with an Account Manager and is at no cost to you. Tell us what is on your mind: a pension you have lost track of, a fixed rate ending, a will you keep meaning to write.